Are wagering markets becoming a new retirement strategy for some young people?
There is disturbing evidence that that answer is yes, especially amongst GenZers.
Global betting on the two largest prediction markets, Kalshi and Polymarket are a colossus. As of June 2026 over $45 billon was wagered on these platforms.
Here’s where the dollars crossed the retirement Rubicon from gambling to investing.
According to Betterment Guidance Gap:
A recent publication claimed that of Gen Z redirected funds intended for investing into wagering and that 26 percent see sports gambling as part of their retirement investment game plan. nearly 4 in 10 men between 18 and 34 use prediction markets, and young people make up up to 60 percent of all users in the same age range.
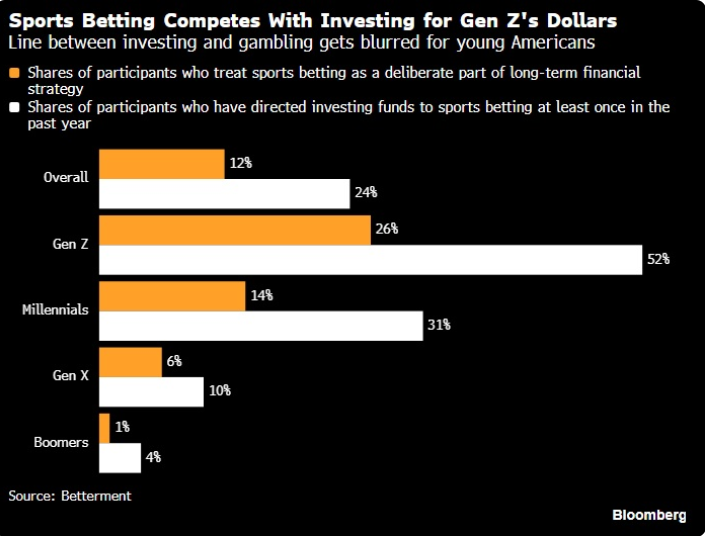
There is some dispute to these figures with other studies showing the actual proportion between 14 and 30 percent but these numbers are still significant.
What is most alarming about the New 401(k) is the game is rigged. While many young men deem themselves experts on all thing sports-related, the facts tell a different tale.
Like stock pickers, few beat the market. Math with hope isn’t a strategy. Not being able to discern that volatility you can explain is investing while volatility you can’t stop watching is gambling is the kiss of death.
The sports book make a killing at your expense.
2024 gaming revenue rose to a record $13.71 billion in 2024, smashing the previous years record of $11.04 billion.
For those who prevail against the infinitesimal odds, the results aren’t anything to write home about. The top 1% of gamblers earn in the range of the low five-figures. Betting on a salary equivalent to a part-time job’s wages isn’t a wise decision to plan one’s retirement around.
Making things worse, the sports books play a game of tails they win, heads you lose.
Having two 23 old sons, I see how the game is played.
The sports books best customers are losers. They reward these poor souls with lavish gifts like free bets and other perks in order to drain their pockets.
The house doesn’t need you to be wrong, it just needs you to keep playing.
All is wonderful until you start to win. When cashing in bets become the norm, limits are substantially reduced making it impossible to reap substantial gains.
Sometimes accounts are frozen making wagering impossible unless you go somewhere else and set up a burner account or gamble in a friends name until the jig is up.
To be blunt, if the average person thinks gambling is a viable retirement strategy, there must be a lot of good drugs out there.
What should we do about this unsettling situation?
Instead of trashing invaluable years of compounding which can never be redeemed, how about throwing some of that parlay stash into the markets and take your chances?
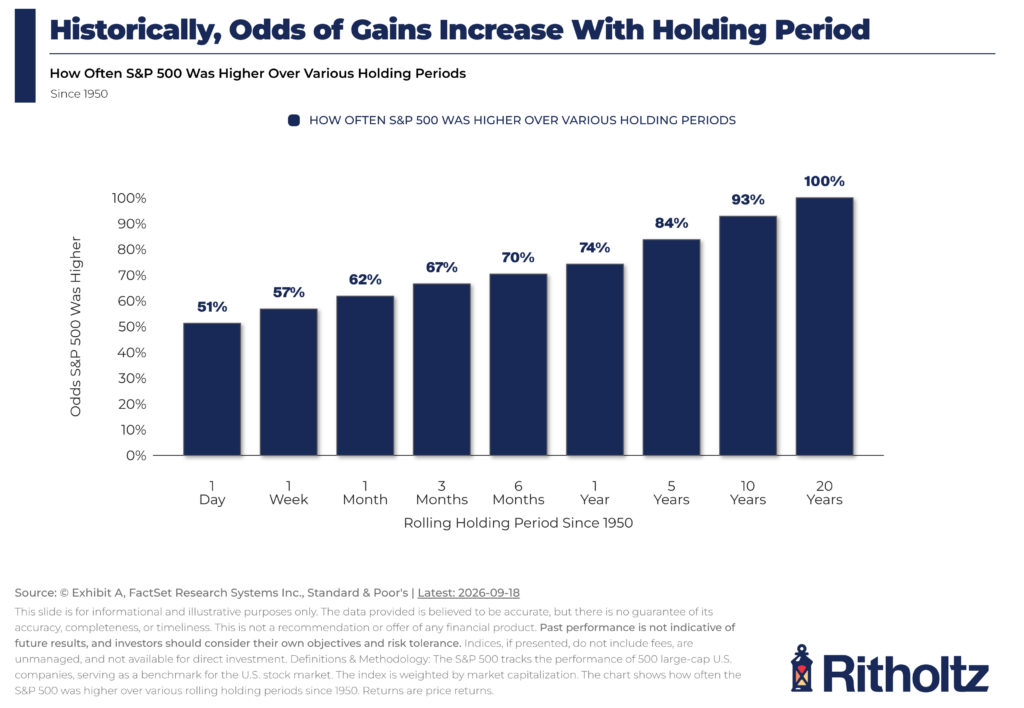
This chart should be a required disclaimer on every gambling app.
Heads they lose, tails you win.
There has NEVER been a 20 year period where investors in a well diversified portfolio lost money. This strategy may not be as exciting as making in-game wagers or hitting a 5-leg parlay but it works, all the time.
A 401(k) compounds. A Parlay multiplies risk. Know the difference.
Nobody is saying that young people should never gamble. Tossing a few dollars into a five leg parlay you can afford to lose isn’t the end of the world.
Thinking that your gambling acumen will finance your retirement is a another story.
You can’t dollar-cost average a coin flip.